A household can have a strong income while still finding mortgage affordability complicated if part of that income comes from overtime, commission, bonuses or multiple jobs. Lenders do not necessarily treat every payment on a payslip in the same way. Preparation and accurate documentation can make complex-income cases easier to understand.
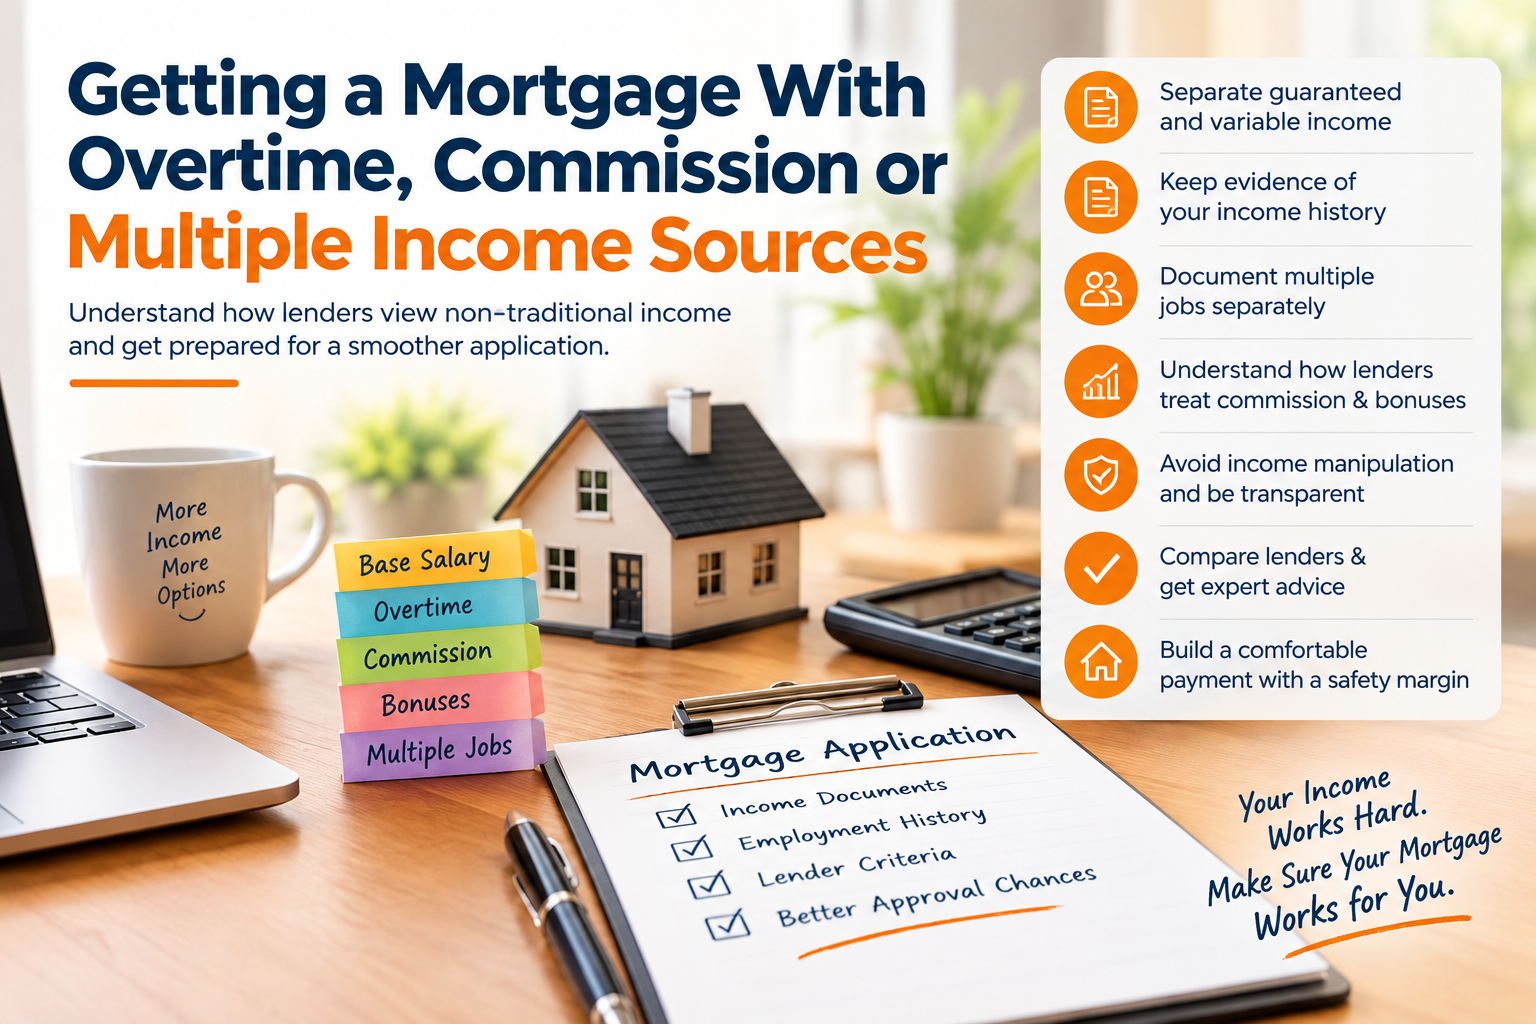
Separate guaranteed and variable income
Start by separating basic salary from overtime, commission, bonus and other variable payments. This gives a clearer picture of the household’s dependable income. A lender may consider regular variable income using historic evidence, while an occasional payment may be treated differently. The exact method varies by lender.
Keep evidence of income history
Payslips, P60s, employment contracts and other records can help demonstrate how variable income has developed. If overtime has been regular for several years, that history may be more informative than one unusually high month. Organise documents before the application so the lender can assess the income accurately.
Multiple jobs need separate documentation
If you have two or more jobs, keep evidence for each role. The lender may consider employment length, hours and income separately. A newly started second job may be treated differently from a long-established position. Accurate information is important because the lender will verify the income during underwriting.
Commission can fluctuate
Commission-based earnings can vary with sales, performance or seasonal conditions. Lenders may use historic averages or apply their own criteria. Do not assume that a strong recent month will automatically be used in full. A consistent history can provide more useful evidence.
Bonus income may be assessed differently
A contractual bonus and a discretionary bonus may not be treated in the same way. Keep the relevant employment documentation and historic payment evidence. If the bonus is a significant part of the borrowing calculation, lender selection becomes especially important.
Recent employment changes
A new job can mean higher income but less employment history. A probation period or changed contract may affect the evidence available. If a job change is already planned, consider how the timing interacts with a mortgage application. Do not make an employment change solely to achieve a particular borrowing figure without considering wider consequences.
Avoid manipulating income figures
Mortgage applications should reflect genuine income. Do not move money between accounts or alter financial arrangements simply to make the application appear stronger without understanding the implications. The lender will assess the evidence and may ask for explanations of unusual transactions.
Specialist lender comparison
Prestige Mortgage Solutions Ltd can help applicants with complex income understand how lender criteria may apply. The aim is to identify an appropriate route and prepare accurate evidence, not to guarantee an approval.
Build some margin into the payment
Where variable income is significant, consider whether the mortgage remains comfortable using a conservative income assumption. This is a personal budgeting decision as well as a lender calculation. A mortgage that requires every bonus to arrive on time can leave little flexibility.
Do not hide changes in income
If your earnings have recently fallen, explain the current position rather than presenting an old higher figure as though it remains current. Lenders assess current circumstances and may request updated documents.
Check whether multiple jobs are sustainable
If you rely on two jobs to meet affordability, consider the practical sustainability of the arrangement. Working hours, commuting and job security can affect the household budget. The mortgage should not depend on an unrealistic assumption that every income source will continue unchanged.
Understand the employer’s documentation
Employment contracts, bonus schemes and commission structures can provide context. If the income is contractual, retain the relevant paperwork. If it is discretionary, historic payment evidence may be more important. The lender decides how it will use the information.
Keep a consistent record of variable income
Where overtime or commission forms part of your income, a consistent history can be useful evidence. Keep records over time rather than relying on a single high month. This can help show whether the variable income is a regular part of your employment or an occasional payment.
Review your income after completion
If variable earnings increase, you may later consider overpayments if the mortgage permits them. If earnings fall, review the household budget early. A mortgage should remain part of a wider financial plan.
Compare lender treatment
One lender may count a proportion of variable income while another may use a different method. This can produce different affordability outcomes for the same applicant. Understanding criteria before a full application can save time.
Avoid last-minute financial changes
Opening new credit, moving large sums between accounts or changing employment shortly before an application can create additional questions. If a change is necessary, disclose it and keep the relevant evidence. Do not attempt to disguise a transaction.
Consider the stability of each income source
Two jobs can increase total income, but the household should also consider how secure each role is. A mortgage should not rely on an income source that is expected to end shortly after completion unless the financial plan has been assessed accordingly.
Keep employer evidence
Contracts, payslips, bonus letters and other employer documents can explain how income is structured. If your commission or bonus scheme has changed, keep the relevant updated documentation. The lender may ask for evidence during underwriting.
Create a conservative income figure
If variable income is important to your mortgage, calculate a conservative personal estimate using a realistic history rather than the highest recent month. This helps you understand what payment would remain comfortable even if variable earnings fluctuate.
Think about future income changes
If a second job is temporary, a commission structure is changing or a promotion is expected, consider how the mortgage will fit the likely future position. Do not assume that an expected increase will definitely occur. The safest budget is one that remains manageable under reasonable variations in income.
Keep income evidence current
Do not rely on old payslips if your employment or pay structure has changed. Keep recent documents and make sure the information submitted reflects the current position. If a lender requests additional evidence, provide it promptly and consistently.
Use realistic assumptions for variable earnings
If the mortgage depends on overtime, commission or bonus income, consider what happens during a weaker month or year. A household budget based entirely on the highest historic income can create unnecessary pressure. A conservative personal budget can provide a useful check alongside the lender’s formal calculation.
Keep future employment changes in mind
A borrower may expect a promotion, career change or move from one role to another. Future income should not be treated as guaranteed unless it is already supported by appropriate documentation. When circumstances are changing, discuss the timing of the mortgage application with an adviser. A lender can assess the evidence available at the time of application, but it cannot base a decision solely on an informal expectation of future earnings.
Think about how income would look without the variable element
One useful personal budgeting exercise is to calculate the mortgage payment against basic guaranteed income and then separately consider the contribution from overtime, commission or bonuses. If the mortgage is comfortable only when every variable payment is received, the household may have limited flexibility. A conservative budget does not mean a lender will ignore valid variable income; it simply gives the borrower a clearer understanding of personal affordability. This can be especially useful for households with seasonal work or commission-heavy employment.
Check the income calculation before relying on it
If a mortgage depends heavily on variable income, ask how the relevant lender calculates that income and what evidence is required. This can prevent a mismatch between the figure you expect and the figure the lender actually uses. The clearer the income history and supporting documentation, the easier it is to understand the likely affordability position.
Frequently Asked Questions
Can overtime count toward mortgage affordability?
It can, depending on the lender’s criteria and the history of the overtime. Evidence may be required.
Can commission income be used?
Some lenders consider commission, but the amount and method can vary. Historic evidence is often important.
Can I use income from two jobs?
Multiple employment income can sometimes be considered, subject to lender rules and employment history.
How is bonus income treated?
Treatment varies between lenders and can depend on whether the bonus is contractual, regular or discretionary.
Should I change jobs before applying for a mortgage?
A job change can affect the evidence available. If a change is already planned, discuss the timing with an adviser rather than changing jobs solely for borrowing purposes.
Conclusion
Mortgage decisions are easier to manage when the full financial picture is understood before an application is made. For readers considering mortgage with overtime Glasgow, preparation should focus on genuine affordability, lender criteria, property information and the long-term cost of the borrowing. Professional advice can help explain the available routes, but the final decision should always reflect the borrower’s own circumstances and the terms of the mortgage offered.